NPS vs Mutual Fund SIP for Retirement: Key Differences
Insights on strategy, resilience, and wealth management in an evolving financial landscape.
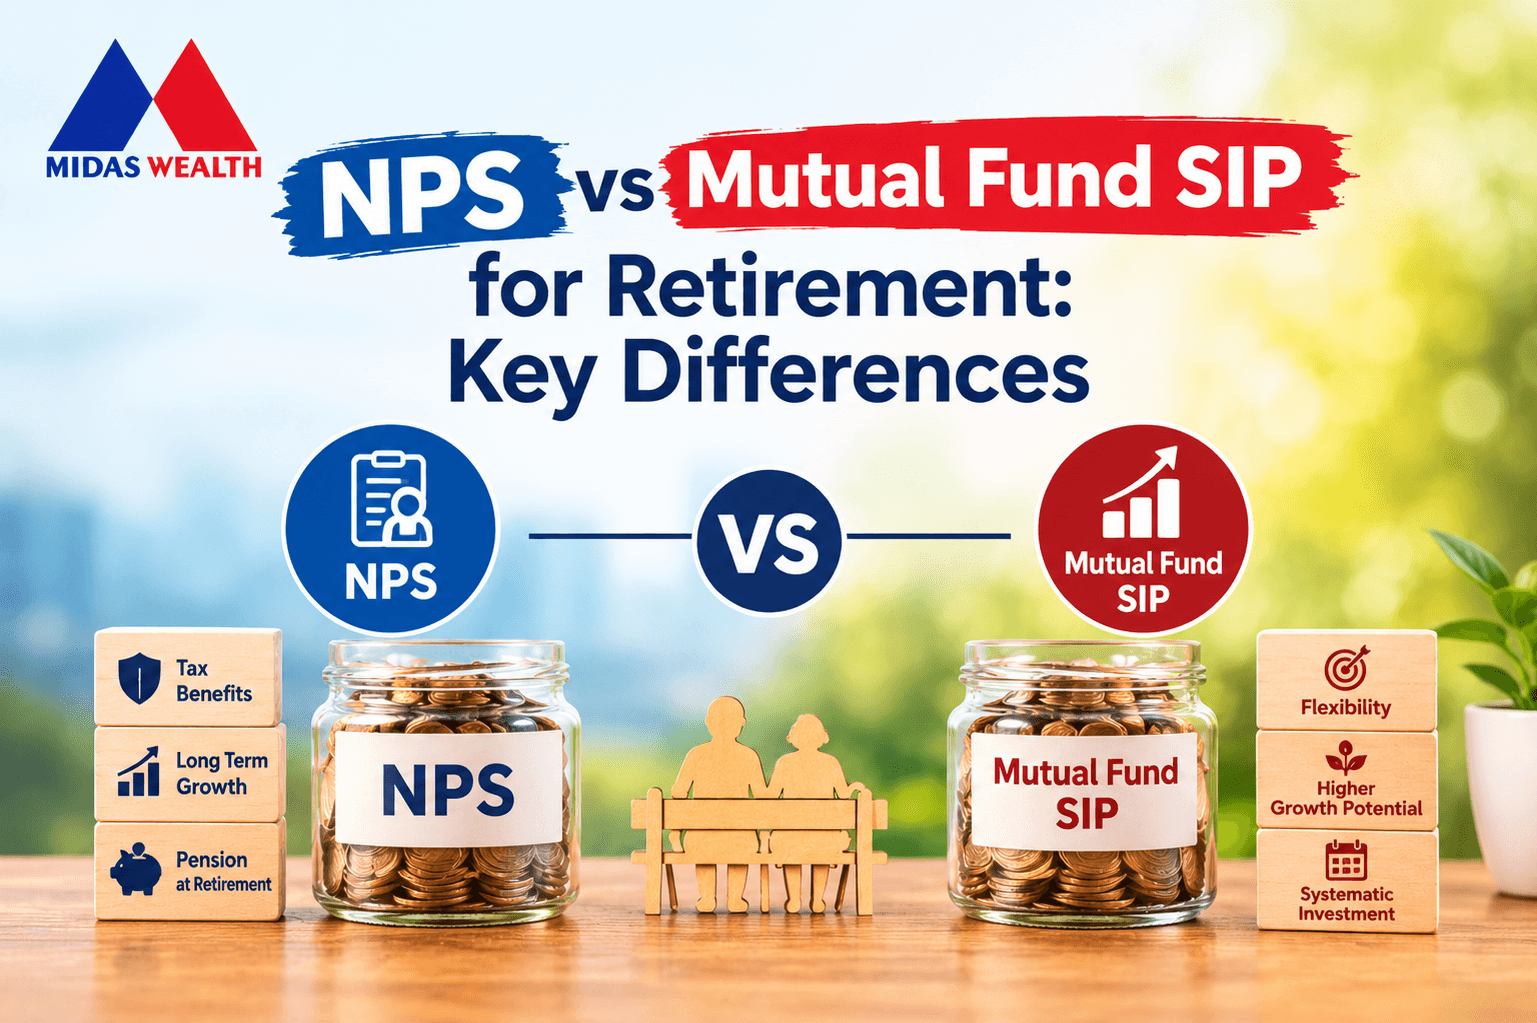
Retirement planning is about building enough money to maintain your lifestyle when you stop working. In India, the National Pension System (NPS) and mutual fund Systematic Investment Plans (SIPs) are two popular ways to invest for long-term financial goals.
Both options allow you to invest regularly and benefit from potential long-term growth. However, they differ in tax benefits, withdrawal rules, investment flexibility, and retirement income options. Understanding these differences can help you decide which option suits your financial situation.
NPS vs Mutual Fund SIP: Key Differences
| Feature | NPS | Mutual Fund SIP |
|---|---|---|
| Main Purpose | Dedicated retirement pension account | Flexible investment method for all goals |
| Lock-in Period | Until age 60 (with restricted partial exits) | None for open-ended funds (3 yrs for ELSS) |
| Tax Benefits | Section 80CCD(1), 80CCD(1B), and 80CCD(2) | Only ELSS qualifies under 80C; regular capital gains apply |
| Liquidity | Strict withdrawal guidelines | High; redeemable anytime on business days |
| Maturity Rule | Min 40% annuity purchase mandatory | 100% lump sum or SWP (Systematic Withdrawal Plan) |
Retirement Compounding Example: ₹5,000/Month for 25 Years
Suppose an investor starts saving ₹5,000 every month at age 35 for 25 years until age 60 (Total invested = ₹15,00,000). At an illustrative 10% annualised return, the accumulated corpus grows to approximately ₹66 lakh.
With NPS, at age 60, up to 60% (₹39.6 lakh) can be withdrawn tax-free as a lump sum, while at least 40% (₹26.4 lakh) is used to buy an annuity providing lifelong monthly pension. With a Mutual Fund SIP, the entire ₹66 lakh is accessible to structure an automated monthly SWP tailored to your exact tax and cash-flow requirements.
Can You Invest in Both NPS and Mutual Fund SIPs?
Yes! Combining both gives you the disciplined lock-in and exclusive Section 80CCD(1B) tax benefits of NPS, alongside the superior liquidity, flexibility, and wealth-growth potential of Mutual Fund SIPs.
Frequently Asked Questions
Which Offers Higher Returns, NPS or Mutual Fund SIP?
Neither guarantees returns. Pure equity mutual funds can offer up to 100% equity exposure, whereas NPS equity allocation (Scheme E) has regulatory percentage caps for conservative management.
Can I withdraw mutual fund investments anytime?
Yes, open-ended mutual funds can be redeemed on any business day, subject to applicable exit loads and capital gains tax rules.
Conclusion
NPS is ideal for investors seeking structured, forced retirement discipline and tax benefits. Mutual fund SIPs provide flexibility and liquidity to adapt to evolving life goals.
Plan your retirement with a goal-based investment strategy. Explore our Mutual Fund Services and Retirement Planning Services at Midas Wealth Advisory.
Important Notice: Mutual fund investments are subject to market risks. Read all scheme related documents carefully.