How to Create a Financial Plan for Your Family
Insights on strategy, resilience, and wealth management in an evolving financial landscape.
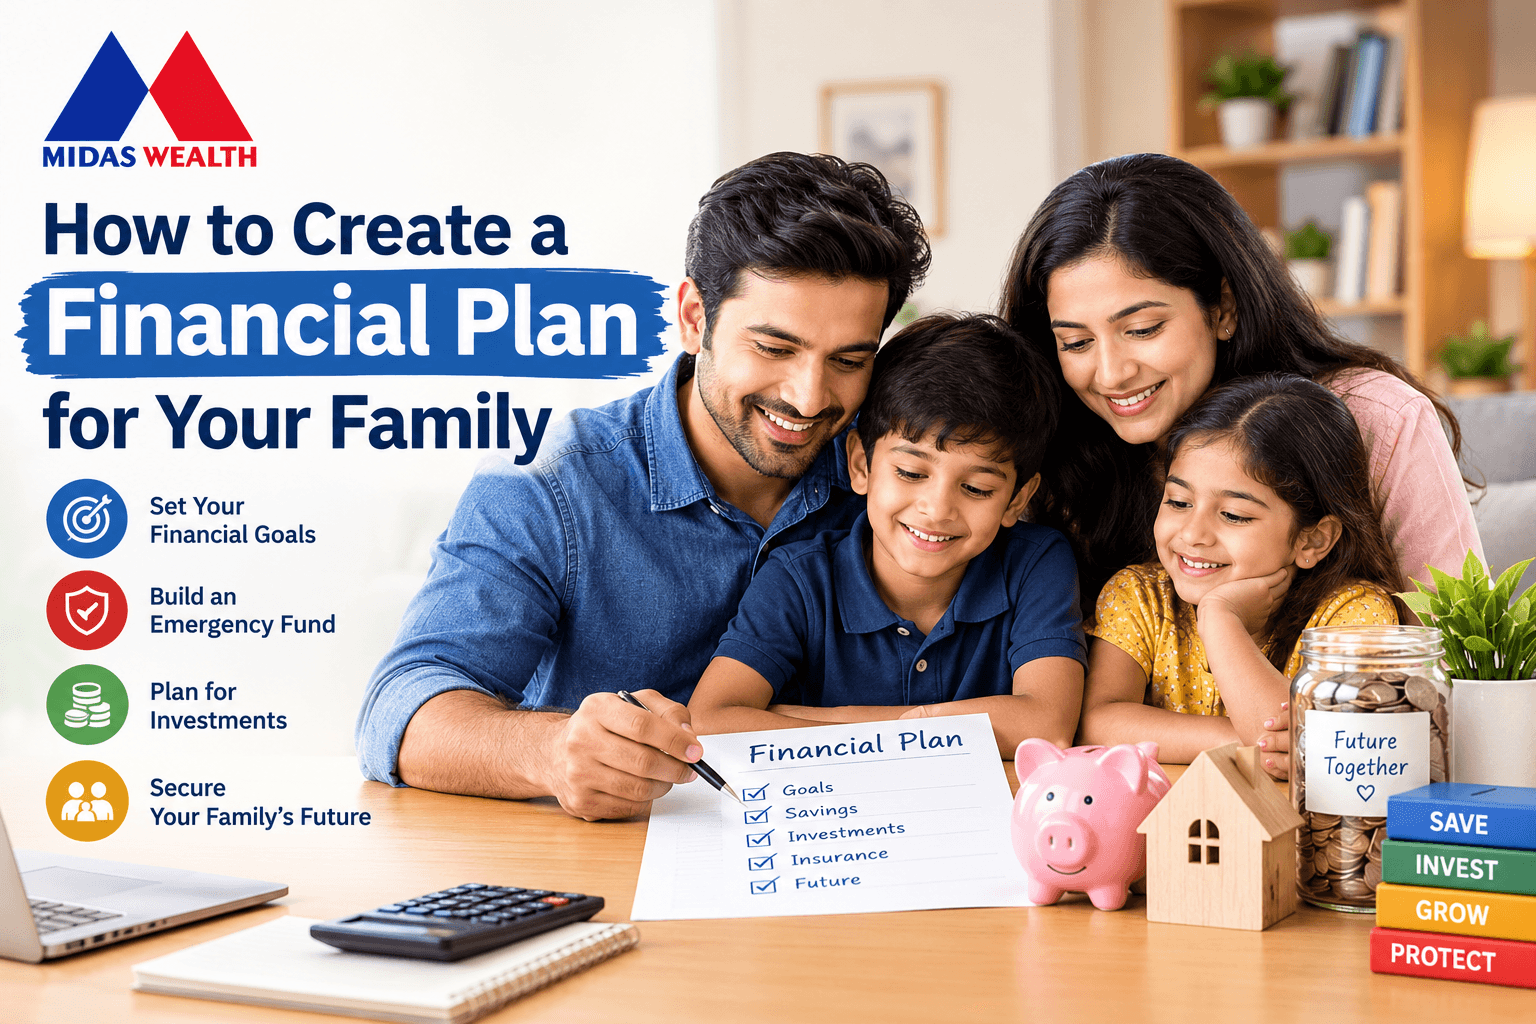
Managing family finances involves more than paying monthly bills. It also means preparing for emergencies, saving for your children's education, buying a home, and building a secure retirement. Without a clear financial plan, it can become difficult to balance daily expenses with long-term goals.
Family financial planning helps you understand where your money goes, how much you can save, and which investments may support your future needs. Whether your household has one income or multiple earners, a practical financial plan can help you make better financial decisions.
10-Step Guide to Creating a Family Financial Plan
Step 1: Calculate Total Family Income
Sum all regular household earnings: salaries, business income, rental yield, and dividends.
Step 2: Track Monthly Outflows
Classify expenses into essentials (rent, EMIs, groceries, school fees) and discretionary (dining out, entertainment, holidays).
Step 3: Define Time-Bound Goals
Document targets with deadlines: home down payment in 3 years, higher education fund in 10 years, retirement in 25 years.
Step 4: Establish a 50/30/20 Family Budget
Target allocating roughly 50% for necessities, 30% for lifestyle, and at least 20% towards savings and investments.
Step 5: Build an Emergency Reserve
Maintain 3 to 6 months of mandatory household expenses in liquid, accessible accounts.
Step 6: Insure What Matters
Secure adequate pure term life insurance for primary breadwinners (15-20x annual income) and comprehensive health insurance for all members.
Step 7: Choose Suitable Investments
Deploy monthly surpluses into equity mutual funds, PPF, NPS, and debt funds matched to each goal's timeline.
Step 8: Plan for Child Higher Education
Factor in higher education inflation (often 10-12% p.a.) when projecting future college fee requirements.
Step 9: Prioritise Retirement
Never sacrifice your retirement corpus entirely for children's expenses; you can get an education loan, but no one loans you retirement funds.
Step 10: Annual Family Review
Review asset allocations, insurance coverage, and goal milestones at least once every 12 months.
Sample Monthly Budget for a ₹80,000 Household
| Expense or Financial Goal | Monthly Allocation |
|---|---|
| Rent or Home Loan EMI | ₹18,000 |
| Groceries & Household Supplies | ₹10,000 |
| Utilities, Fuel & Transport | ₹7,000 |
| School Fees & Healthcare | ₹5,000 |
| Insurance Premiums (Life & Health) | ₹3,000 |
| Emergency Savings Reserve | ₹5,000 |
| Investments & Retirement Savings | ₹12,000 |
| Personal Spending, Dining & Leisure | ₹7,000 |
| Additional Savings or Debt Repayment | ₹5,000 |
| Miscellaneous Buffer | ₹8,000 |
| Total Income | ₹80,000 |
Frequently Asked Questions
How Much Emergency Fund Should a Family Have?
Three to six months of mandatory living expenses is the standard recommended reserve. If self-employed or in variable commission roles, aim for 9 to 12 months.
When Should I Consult a Financial Advisor?
Consider consulting a SEBI-registered advisor when managing multiple goals simultaneously, coordinating tax implications, or needing an objective portfolio review.
Conclusion
Take control of your family's financial future with a goal-based plan. Explore our comprehensive Financial Planning Services at Midas Wealth Advisory.
Important Notice: This article is for informational purposes only. Consult professional advisors before making significant financial commitments.